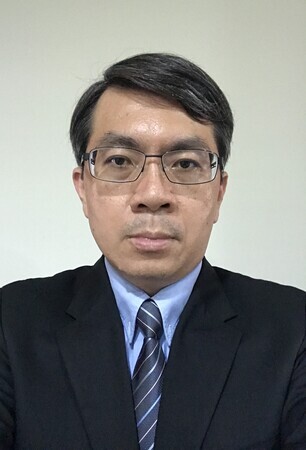
Kuang-Liang Chang
|
Kuang-Liang Chang, Professor |
|
|
Office |
Guoyan 5028 (original location code) |
|
Extension |
5586 |
|
Education |
Ph.D. in Economics, National Taiwan University |
|
|
kuangliangc@mail.nsysu.edu.tw |
|
Areas of Expertise |
Applied Macroeconometrics, Energy Economics, Financial Econometrics, International Finance, Real Estate |
Professional Experience
Chair, Department of Political Economy, National Sun Yat-sen University
Distinguished Professor, National Chiayi University
Visiting Scholar, Hokkaido University
Chair, Department of Applied Economics, National Chiayi University
Professor, Department of Applied Economics, National Chiayi University
Associate Professor, Department of Applied Economics, National Chiayi University
Visiting Scholar, City University of Hong Kong
Assistant Professor, Department of Applied Economics, National Chiayi University
Assistant Professor, Department of Finance, Feng Chia University
Peer-Reviewed Journal Articles and Papers
1. Chang, Kuang-Liang (2025), Differential impacts of stock and housing returns on the conditional distribution of consumption growth rate during the global financial crisis and the COVID ‐19 pandemic: Evidence from Taiwan. Asian-Pacific Economic Literature, Accepted. (SSCI)
2. Chang, Kuang-Liang (2025), Do the impacts of the futures-spot spread and skewness on the interdependence between spot and futures markets differ across regimes and energy commodities markets? Applied Economics, 57, 2979-2997. (SSCI; National Science Council economics field, B-tier journal.)
3. Chang, Kuang-Liang (2023), The low-magnitude and high-magnitude asymmetries in tail dependence structures in international equity markets and the role of bilateral exchange rate. Journal of International Money and Finance, 133, Article 102839. (SSCI; National Science Council finance field, A Tire-1-tier journal [source spelling retained]; economics field, A-tier journal.)
4. Chang, Kuang-Liang (2023), The tail dependence structure between return and trading volume: An investigation on the Bitcoin market. Applied Economics, 55, 1234-1246. (SSCI; National Science Council economics field, B-tier journal.)
5.Chang, Kuang-Liang*, Chingnun Lee, and Chi-Wei, He (2023), Four types of tail dependence structures between U.S. dollar index and S&P 500 stock returns:1990-2019. Applied Economics Letters, 30, 2189-2194. (SSCI)
6.Chang, Jui-Chuan Della and Kuang-Liang Chang* (2023), The asymmetric impacts of international portfolio flows on Australian dollar returns. Applied Economics Letters, 30, 478-483. (SSCI)
7.Chang, Kuang-Liang and Ka Yui Leung* (2022), Chapter 12: How did the asset markets change after the Global Financial Crisis? June 2022, Handbook of Real Estate and Macroeconomics. pp. 312-336.
8. Chang, Kuang-Liang (2022), Do economic policy uncertainty indices matter in joint volatility cycles between U.S. and Japanese stock markets? Finance Research Letters, 47, Article 102579. (SSCI; National Science Council finance field, A-minus-tier journal.)
9. Chang, Kuang-Liang (2021), A New Dynamic Mixture Copula Mechanism to Examine the Nonlinear and Asymmetric Tail Dependence Between Stock and Exchange Rate Returns. Computational Economics, 58, 965-999. (SSCI; National Science Council economics field, B-tier journal.)
10.Chang, Kuang-Liang (2021), Do U.S. and Japanese uncertainty shocks play important roles in affecting transition mechanisms of Japanese stock market? The North American Journal of Economics and Finance, 58, Article 101494. (SSCI)
11. Chan, Kuang-Liang* and Chingnun Lee (2020), The asymmetric spillover effect of the Markov switching mechanism from the futures market to the spot market. International Review of Economics and Finance, 69, 374-388. (SSCI; National Science Council finance field, A-minus-tier journal; economics field, B-tier journal.) [Source spelling retained; profile name: Kuang-Liang Chang.]
12.Chang, Kuang-Liang and Jui-Chuan Della Chang* (2020), Dynamic Dependence between U.S. Inbound Visits and Exchange Rate, Journal of Hospitality and Tourism Research, 44, 1035-1046. (SSCI)
13.Chang, Kuang-Liang (2020), An investigation on mixed housing-cycle structures and asymmetric tail dependences. The North American Journal of Economics and Finance, 51, Article 100864. (SSCI)
14. Chang, Kuang-Liang (2020), Are cyclical patterns of international housing markets interdependent? Economic Modelling, 88, 14-24. (SSCI; National Science Council economics field, B-tier journal.)
15. He, Chi-Wei, Kuang-Liang Chang* and Yung-Jang Wang (2020), Does the jump risk in the US market matter for Japan and Hong Kong? An investigation on the REIT market, Finance Research Letters, 34, Article 101238. (SSCI; National Science Council finance field, A-minus-tier journal.)
16.Chang, Jui-Chuan Della and Kuang-Liang Chang* (2018), The asymmetric effects of U.S. large-scale asset purchases on the volatility of the Canadian dollar futures market, The North American Journal of Economics and Finance, 46, 15-28. (SSCI)
17.Chang, Kuang-Liang (2018), Asymmetric downside and upside co-movements between stock and REIT markets, Applied Economics Letters, 25, 78-82. (SSCI)
18.Chang, Kuang-Liang (2017), Does REIT index hedge inflation risk? New evidence from the tail quantile dependences of the Markov-switching GRG copula, The North American Journal of Economics and Finance, 39, 56-67. (SSCI)
19. Chang, Kuang-Liang* and Shih-Ti Yu (2017), An investigation on the relationship between return and trading volume: Asymmetric V-type or asymmetric increasing-type pattern, Quantitative Finance, 17, 1223-1241. (SSCI; National Science Council finance field, A Tire-2-tier journal [source spelling retained].)
20.Chang, Kuang-Liang (2017), A mixed dependence between the exchange rate and international crude oil returns: An application of dynamic mixture copula, Emerging Markets Finance and Trade, 53, 2347-2360. (SSCI)
21.Chang Kuang-Liang (2016), Does the return-state-varying relationship between risk and return matter in modeling the time series process of stock return? International Review of Economics and Finance, 42, 72-87. (SSCI)
22.Chang, Kuang-Liang, Nan-Kuang Chen and Ka-Yui Leung* (2016), Losing track of the asset markets: The case of housing and stock, International Real Estate Review, 19, 435-492. (RePEC)
23.Chang, Kuang-Liang (2014), The symmetrical and positive relationship between crude oil return and nominal exchange rate return, The North American Journal of Economics and Finance, 29, 266-284. (SSCI)
24.Chang, Kuang-Liang* and Ming-Hui Yen (2014), The magnitude and significance of macroeconomic variables in explaining regional housing fluctuations, Economics Bulletin, 34, 828-841. (EconLit)
25.Chang, Kuang-Liang* and Shih-Ti Yu (2013), Does crude oil price play an important role in explaining stock return behavior? Energy Economics, 39, 159-168. (SSCI)
26.Chang, Kuang-Liang, Nan-Kuang Chen and Ka Yui Leung* (2013), In the Shadow of the United States: The International Transmission Effect of Asset Returns, Pacific Economic Review, 18, 1-40. (SSCI)
27.Liu, Wen-Hsien*, Ching-Fang Chung and Kuang-Liang Chang (2013), Inventory Change, Capacity Utilization and the Semiconductor Industry Cycle, Economic Modelling, 31, 119-127. (SSCI)
28.Chen, Ho-Chyuan, Kuang-Liang Chang* and Shih-Ti Yu (2012), Application of the Tobit model with autoregressive conditional heteroscedasticity for foreign exchange market interventions, Japan and the World Economy, 24, 274-282. (SSCI)
29.Chang, Kuang-Liang (2012), The time-varying and asymmetric dependence between crude oil spot and futures markets: Evidence from the Mixture copula-based ARJI–GARCH model, Economic Modelling, 29, 2298-2309. (SSCI)
30.Chang, Kuang-Liang (2012), The impacts of regime-switching structures and fat-tailed characteristics on the relationship between inflation and inflation uncertainty, Journal of Macroeconomics, 34, 523-536. (SSCI)
31.Chang, Kuang-Liang, Nan-Kuang Chen and Ka Yui Leung* (2012), The dynamics of housing returns in Singapore: How important are the international transmission mechanisms? Regional Science and Urban Economics, 42, 516-530. (SSCI)
32.Chang, Kuang-Liang (2012), Volatility regimes, asymmetric basis effects and forecasting performance: An empirical investigation of the WTI crude oil futures market, Energy Economics, 34, 294-306. (SSCI)
33.Chang, Kuang-Liang (2012), Analysis of structural changes in the relationship between regional housing markets in Taiwan, Economics Bulletin, 32, 2220-2230. (EconLit)
34.Chang, Kuang-Liang, Nan-Kuang Chen and Ka Yui Leung* (2011), Monetary policy, term structure and asset return: Comparing REIT, housing and stock, The Journal of Real Estate Finance and Economics, 43, 221-257. (SSCI)
35.Chang, Kuang-Liang (2011), The nonlinear effects of expected and unexpected components of monetary policy on the dynamics of REIT returns, Economic Modelling, 28, 911-920. (SSCI)
36.Chang, Kuang-Liang (2010), House price dynamics, conditional higher-order moments, and density forecasts, Economic Modelling, 27, 1029-1039. (SSCI)
37.Chang, Kuang-Liang* and Chi-Wei He (2010), Does the magnitude of the effect of inflation uncertainty on output growth depend on the level of inflation? Manchester School, 78, 126-148. (SSCI)
38.Chang, Kuang-Liang (2010), The optimal value-at-risk hedging strategy under bivariate regime switching ARCH framework, Applied Economics, 43, 2627-2640. (SSCI)
39.Chang, Kuang-Liang (2009), Do macroeconomic variables have regime-dependent effects on stock return dynamics? Evidence from the Markov regime switching model, Economic Modelling, 26, 1283-1299. (SSCI)
Conference Papers
1. Chang, Kuang-Liang (2025), The impact of exchange rate and skewness on stock returns. 2025 Taiwan Finance Association (TFA) Annual Meeting and International Conference, June 6, 2025.
2. Chang, Kuang-Liang (2024), Time-varying and asymmetric dependencies among bank loans, housing market, and stock market:An application on the canonical- vine copula with a mixed copula structure in each pair-copula construction. The 18th NYCU International Finance Conference & 4th Yushan Conference, December 6, 2024.
3. Chang, Kuang-Liang (2023), Do the Role s of Financial Assets on the Personal Consumption Expenditure Differ in the Financial Crisis and Covid 19 pandemic? Evidence from Taiwan. The 14th Biennial Conference of Asian Consumer and Family Economics Association, Kitakyushu (JAPAN), July 9-12, 2023.
4. Chang, Kuang-Liang and Ka-Yui Leung (2021), How did the asset markets change after the Global Financial Crisis? 2021 Joint Virtual Real Estate Conference by the Asian Real Estate Society (AsRES), the Global Chinese Real Estate Congress (GCREC) and the American Real Estate and Urban Economics Association (AREUEA), July 18-21, 2021.
5. Chang, Kuang-Liang (2020), Do uncertainty indices affect the transition mechanism of the stock market? Evidence from the Japanese stock market. 2020 Annual Meeting and International Conference of the Taiwan Finance Association, National Chi Nan University, September 25-26, 2020.
6.Chang, Kuang-Liang and Chi-Wei He (2019), The asymmetric relationship between the stock and exchange rate markets: How important is the interaction between dynamic structure and dynamic intensity? WEAI 15th International Conference, Tokyo, March 21-24, 2019.
7. Chang, Kuang-Liang and Jui-Chuan Della Chang (2018), International Portfolio Flows and Exchange Rate in the Commodity Exporting Economy. 2018 Annual Meeting of the Taiwan Economic Association, Chung-Hua Institution for Economic Research, Taipei, December 5, 2018.
8.Chang, Kuang-Liang (2018), Are recession and recovery cycles in international housing markets synchronous or asynchronous? An investigation on US, UK, and Canadian housing markets. 2018 Asian Real Estate Society (AsRES) Annual International conference, South Korea, July 8-11, 2018.
9.Chang, Kuang-Liang and Ka-Yui Leung (2018), Did the asset markets become more or less risky after the Global Financial Crisis? 2018 Asian Real Estate Society (AsRES) Annual International conference, South Korea, July 8-11, 2018.
10. Chang, Jui-Chuan Della and Kuang-Liang Chang (2017), Investigating the dynamic dependence between exchange rate and overseas visits to the U.S. in a time-varying copula model. The 11th NCTU International Finance Conference, Taiwan, December 8, 2017; 2017 Annual Meeting of the Taiwan Economic Association, National Tsing Hua University, Hsinchu, December 16, 2017.
11.Chang, Kuang-Liang (2017), The relative importance of co-jump and idiosyncratic jump on the dynamic relationship between US and Asia securitized real estate markets. 2017 Annual Conference of Asian Real Estate Society (AsRES), Taiwan, July 9-12, 2017
12. Chang, Kuang-Liang (2016), Assessing the economic index of riskiness and economic performance index: An investigation on real estate, REITs and stock markets, 2016 Annual Meeting and International Conference of the Taiwan Finance Association, National Taipei University, New Taipei City, May 27-28, 2016.
13. Kuang-Liang Chang (2016), Does the real-estate asset risk-premium puzzle exist? 2016 Annual Meeting and Paper Conference of the Housing Society, National Pingtung University, Pingtung, January 9, 2016.
14.Chang, Kuang-Liang (2016), An investigation on the magnitude of time-varying and quantile-varying relationship between price and trading volume: Asymmetric v-type or asymmetric increasing-type pattern, The 9th NCTU International Finance Conference, Hsinchu, January 8, 2016.
15.Chang, Kuang-Liang (2015), An investigation on the magnitude of time-varying and quantile-varying relationship between price and trading volume: V-type or increasing-type pattern. 21st Computing in Economics and Finance, Taipei, June 20 -22, 2015.
16.Chang, Kuang-Liang (2014), Do stock and REITs hedge inflation risk?An application of Markov-switching copula specification. 2014 Asia Conference on Economics & Business Research, Singapore, November 13 - 14, 2014.
17.Leung, Ka-Yui, Kuang-Liang Chang and Nan-Kuang Chen (2014), Losing Track of the Asset Markets: the Case of Housing and Stock. 2014 Asian Meeting of the Econometric Society, Taipei City, June 20-22, 2014.
18.Chang, K. L., N. K. Chen and Ka-Yui Leung (2010) Asymmetric, Non-Linear, and EGARCH Effects of Monetary Policy on the Mean and Volatility of Housing Returns. The 15th Asian Real Estate Society (AsRES) International Conference, Kaohsiung City, July 9-12, 2010。
19. Kuang-Liang Chang (2010), Are the dynamics of stock returns and volatility governed by different regime-switching variables? An application of the DRV-AR-GARCH model, 2010 Cross-Strait Finance Conference, Tunghai University, Taichung, January 16, 2010.
20. Chang, K. L., N. K. Chen and K. Y. Leung (2008) Monetary Policy, Term Structure and Asset Return: Comparing REIT, Housing and Stock. 2008 Annual Meeting of the Taiwan Economic Association, December 20, 2008, Taipei.
21. Kuang-Liang Chang, Housing-Price Dynamics and Conditional Higher-Order Moments in the United Kingdom and the United States, Annual Meeting and Academic Conference of the Taiwan Finance Association, jointly organized by the Taiwan Finance Association and National Dong Hwa University, Hualien, June 8-9, 2008.
22. Kuang-Liang Chang, Optimal Value-at-Risk Hedging Strategy and Hedging Performance under a Regime-Switching Specification, 2007 Annual Meeting and Academic Conference of the Taiwan Finance Association, Taichung.
Research Projects
ROC 114 (2025) Thematic Research Project (General Research Project): The Contributions of Markov Regime-Switching Jump Risk and Non-Jump Risk to Stock Risk Premiums—An Application of a Markov Regime-Switching Multivariate GAS Model with Jump Factors.
ROC 113 (2024) Thematic Research Project (General Research Project): Using a Skewed-Student T Distribution’s Scale and Skewness Parameters with GAS Dynamics in a Skewness-in-Mean Model to Examine the Effects of Conditional Skewness on Expected Stock Returns.
ROC 112 (2023) Thematic Research Project (General Research Project): Using a Time-Varying and Asymmetric Mixed-Form Canonical Vine copula Model to Examine the Relationships among Bank Lending, Stock Markets, and Real-Estate Markets.
ROC 111 (2022) Thematic Research Project (General Research Project): A Markov Regime-Switching GAS Mixed Dependence-Structure Model for the Effects of Bilateral Exchange Rates on Asymmetric Tail Dependence in International Stock Markets.
ROC 109 (2020) Thematic Research Project (General Research Project): The Effects of the Relationship between Markov Regime-Switching Mechanisms in Marginal Distributions and in copula Functions on Correlation Structures in International Stock Markets.
ROC 108 (2019) Thematic Research Project (General Research Project): Financial-Stress Indices, Economic-Policy-Uncertainty Indices, and International Stock Markets.
ROC 107 (2018) Thematic Research Project (General Research Project): The Importance of Dynamic Dependence Structures and Dynamic Dependence Strength in Relationships between Stock and Foreign-Exchange Markets.
ROC 106 (2017) Thematic Research Project (General Research Project): Regional Housing-Price Dependence and Downward Rigidity in Housing Prices—An Application of a Composite copula Specification with a Markov Regime-Switching Dependence Mechanism.
ROC 105 (2016) Thematic Research Project (General Research Project): A Multiple Markov Regime-Switching Dynamic-Correlation GARCH Model with a Markov Regime-Switching Jump Process for Dynamic Hedging Strategies and Financial-Asset Correlations.
ROC 104 (2015) Thematic Research Project (General Research Project): Re-examining the Real-Estate Asset Risk-Premium Puzzle Using the Economic Performance Measure Proposed by Homm and Pigorsch (2012).
ROC 103 (2014) Thematic Research Project (General Research Project): The Nonlinear Relationship between Energy-Futures Returns and Trading Volume—Evidence from a Time-Varying Mixture copula Method at Different Quantiles.
ROC 102 (2013) Thematic Research Project (General Research Project): The Ability of Stocks and Real-Estate Investment Trusts to Hedge Inflation Risk—An Application of an MS-AR-GARCH-SJC-Copula Specification.
ROC 101 (2012) Thematic Research Project (General Research Project): Using a Markov Regime-Switching ARJI-GARCJH-TVTP Model to Investigate the Effects of Crude-Oil Price Changes on Stock Prices and Stock Value-at-Risk.
ROC 100 (2011) Thematic Research Project (General Research Project): Using a mixture copula-based ARJI-GARCH Model to Formulate Dynamic Futures-Hedging Strategies.
ROC 099 (2010) Thematic Research Project (General Research Project): An Examination of Crude-Oil Price Dynamics and Higher-Order Moment Behavior.
ROC 096 (2007) Thematic Research Project (General Research Project): The Effects of Macroeconomic Variables in Different Regimes on Stock Returns, Volatility, and Regime-Transition Probabilities: Evidence from a Markov Regime-Switching Model.
ROC 095 (2006) Thematic Research Project (General Research Project): Formulating an Optimal Value-at-Risk Hedging Strategy: An Application of a Bivariate Regime Switching AR-ARCH (SWARCH) Model.